Military Tax in Ukraine in 2026: Who Pays, How Much and When

In 2026, almost everyone pays the military levy: employees, Sole Proprietors under all tax systems, landlords, and those who receive income from abroad. However, the rates and rules differ for each category, and this is where most mistakes occur.
Most entrepreneurs do not even realize that for Sole Proprietors under the simplified tax system, the military levy does not depend on income at all. Whether you earned UAH 5,000 or UAH 500,000, the amount is the same, and it must be paid in advance, by the 20th day of the current month.
Let's break down the 2026 figures: how much each category pays, the payment deadlines, who is exempt, and how long the levy will remain in effect.
Who pays the military levy
The list of taxpayers is established by clause 16-1 of subsection 10 of section XX of the Tax Code. There are three categories.
- Individuals - residents with any income and non-residents with income sourced in Ukraine, as well as tax agents that withhold the levy;
- Sole Proprietors in simplified tax groups 1, 2, and 4 - a fixed amount;
- Simplified tax group 3 taxpayers - both entrepreneurs and legal entities, except e-residents.
Important for Sole Proprietors under the general tax system. They are not explicitly listed, but they fall into the first category as ordinary individuals and must pay the levy. We cover this separately below.
For Sole Proprietors under the simplified tax system, the levy took effect on January 1, 2025 - before that, they did not pay it at all.
Military levy rates in 2026
The rate depends not on the amount of income, but on the taxpayer category you belong to.
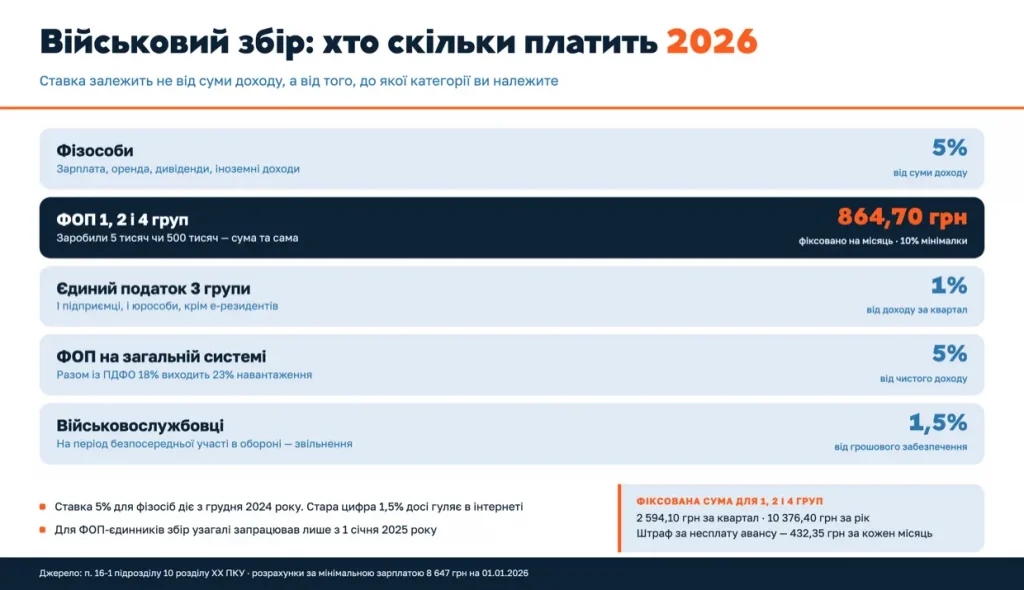
The key difference is between the simplified tax groups. Groups 1, 2, and 4 pay a fixed amount regardless of revenue. Group 3 pays a percentage of actual income - the same income used to calculate the single tax.
For groups 1, 2, and 4, the amount is the same and is calculated based on the minimum wage as of January 1 - in 2026, it is UAH 8,647.
This comes to UAH 864.70 per month, UAH 2,594.10 per quarter, or UAH 10,376.40 per year.
For group 3, the calculation is different: 1% of quarterly income. So, with turnover of UAH 200,000 per quarter, the levy will be UAH 2,000 - on top of the 5% single tax.
Together with the single tax and Unified Social Contribution, the military levy forms part of the monthly tax burden that should be factored into your calculations in advance.
When to pay the military levy: deadlines for Sole Proprietors
The deadlines vary between groups, and confusion over them is the most common cause of accidental tax debt.
| Who | Payment deadline | Who calculates it |
|---|---|---|
| Sole Proprietors in groups 1, 2, and 4 | In advance, no later than the 20th day of the current month | Tax authority |
| Simplified tax group 3 | 10 calendar days after the deadline for the quarterly tax return | Taxpayer independently |
| Sole Proprietors under the general tax system | By August 1 of the following year, based on the annual tax return | Taxpayer independently |
For groups 1, 2, and 4, the levy is paid in advance - for August, it must be paid by August 20, not in September. You can pay in advance for a quarter or for the entire year, but not beyond the end of the current year.
There is no separate military levy tax return. The amounts are reported as part of the simplified taxpayer's tax return, so no additional reporting is required.
The late-payment penalty for groups 1, 2, and 4 is 50% of the levy rate, or UAH 432.35 for each unpaid month. For group 3, the general penalties for late tax payment apply: from 5% to 50%, depending on the length of the delay. All deadlines are listed in the tax calendar for Sole Proprietors.
How the military levy is withheld from salary
The employee does not need to do anything - the employer handles everything. The employer withholds the levy from the accrued salary and transfers it to the state budget.
The deadline is the same day the salary is paid, using a single payment document. The bank will simply not process the salary payment unless the corresponding tax payment order is submitted at the same time.
There are two exceptions:
- if the salary is paid in cash from the cash desk or in kind, the levy must be paid within three business days;
- if the salary has been accrued but not paid, the levy must be transferred within the deadlines established for the monthly reporting period.
Where to report it. The military levy is reported in the Tax Calculation, in Annex 4DF: the accrued amount is shown separately from the amount actually transferred.
Important: the reporting forms changed in summer 2026. Sole Proprietor employers and individuals engaged in independent professional activities now submit quarterly calculations broken down by month, while legal entities submit them monthly. The deadlines are 40 calendar days after the end of the quarter and 20 calendar days after the end of the month, respectively. We covered what else changes when a Sole Proprietor hires their first employee in our article about hiring an employee.
Does a Sole Proprietor under the general tax system pay the military levy?
Yes, 5% - but not on total revenue. It is charged on net income: the difference between income and documented expenses. This is the same tax base used to calculate the 18% personal income tax.
This means the total tax burden on net income is 23%: 18% personal income tax plus 5% military levy.
It is calculated once a year, based on the annual property and income tax return. The payment deadline is August 1 of the following year.
Do not confuse this with advance payments. The advance payments that a Sole Proprietor under the general tax system makes quarterly are advance payments of personal income tax, not the military levy. The Tax Code does not provide for separate quarterly advance payments of the military levy under the general tax system.
What income is subject to the military levy
The rule is simple and universal: if personal income tax is payable on income, the military levy is payable on it as well. If the income is exempt from taxation or taxed at a zero rate, no military levy is due either.
| Income | Military levy |
|---|---|
| Salary | Yes, 5% |
| Rental income from real estate | Yes, 5% |
| Dividends | Yes, 5% |
| Foreign income | Yes, 5% |
| Inheritance from close relatives | No |
| Sale of residential property once a year after 3 years of ownership | No |
| Sale of one vehicle per year | No |
| Second and subsequent sales of vehicles or residential property | Yes, 5% |
There is one exception to the rule - income earned by a Sole Proprietor under the simplified tax system. No personal income tax is charged on it, but the military levy still applies: a separate rule establishes the levy for simplified tax system taxpayers.
If you rent out residential property, the levy is calculated together with personal income tax - see our article on renting out property through a Sole Proprietor for details. The rules for income received from abroad are explained in our article on declaring foreign income.
Who is exempt from the military levy
There are few exemptions, and almost all of them apply only to simplified tax groups 1 and 2.
Groups 3 and 4 are not eligible for these exemptions - neither the tax vacation nor the frontline-area exemption applies to them. Many articles simply say "for simplified tax system taxpayers," which is misleading.
A separate point about illness. The exemption applies only if the illness lasted 30 calendar days or more and is confirmed by an extract from the Electronic Register of Sick Leave Certificates.
The frontline-area exemption is strictly tied to the tax address. If a Sole Proprietor re-registers their tax address in a safe area, the right not to pay the levy ends from the following month. Separate rules apply to entrepreneurs serving in the military - we covered them in our article on taxes for mobilized Sole Proprietors.
Not sure you are paying everything correctly?
The accountants at buh.ua will check your calculations, monitor payment deadlines, help you claim available exemptions, and take care of all your accounting.
How long will the military levy remain in effect?
There are two different answers here, and they are often confused.
The levy itself has no fixed end date. It remains in effect until the Verkhovna Rada adopts a separate decision on the completion of the Armed Forces reform. There is no specific end date.
The increased rates, however, do have a time limit. For Sole Proprietors under the simplified tax system and the 5% rate for individuals, the deadline is tied to martial law: December 31 of the third calendar year following the year in which martial law is lifted.
Example. If martial law is lifted in 2027, Sole Proprietors under the simplified tax system will pay the levy through December 31, 2030. From January 1, 2031, the rate for individuals will return to 1.5%.
This is a recent change introduced in April 2026. Previously, the Tax Code provided for only one year after martial law was lifted - now it is three years. Materials published earlier are outdated in this respect.
FAQ: questions about the military levy
How much military levy does a Group 2 Sole Proprietor pay in 2026?
UAH 864.70 per month - this is 10% of the minimum wage. The amount is the same for groups 1, 2, and 4 and does not depend on income. The annual total is UAH 10,376.40.
Does a Sole Proprietor pay the military levy if they have no income?
Yes. For groups 1, 2, and 4, the levy is fixed and is not linked to revenue, so it must be paid even for months with no transactions at all. For group 3, the levy is calculated based on income, so if income for the quarter is zero, the levy is also zero.
When must a Group 1 Sole Proprietor pay the military levy?
By the 20th day of the current month, in advance. For example, the levy for August must be paid by August 20. The tax authority calculates the amount, and it is reported in the annual simplified taxpayer's tax return.
What is the penalty for failing to pay the military levy?
For groups 1, 2, and 4, the penalty is 50% of the levy rate, which is UAH 432.35 for each unpaid month in 2026. For group 3, the general penalties for late payment apply: 5% or 10% depending on the length of the delay, and 25% or 50% for intentional non-payment.
Does the tax vacation apply to the military levy?
Yes, but only for groups 1 and 2 without employees: one calendar month per year for vacation and a period of illness lasting at least 30 days. An application must be submitted to the tax authority. This exemption does not apply to the Unified Social Contribution.
Is the military levy withheld from apartment rental income?
Yes, 5% - together with 18% personal income tax, making a total of 23% of the rental income. If the tenant is a company or Sole Proprietor, the tenant withholds the amounts; if the tenant is an ordinary individual, the property owner is responsible for paying them.
Until what year will the military levy remain in effect?
The levy itself has no fixed end date - it remains in effect until the Verkhovna Rada adopts a decision on the completion of the Armed Forces reform. However, for Sole Proprietors under the simplified tax system and for the 5% rate applicable to individuals, there is a limit: December 31 of the third calendar year after martial law is lifted.
Conclusion
In 2026, the military levy is paid by everyone who receives taxable income, but the rules differ significantly. For Sole Proprietors in groups 1, 2, and 4, it is a fixed UAH 864.70 per month regardless of revenue, payable in advance by the 20th day of the month. For group 3, it is 1% of quarterly income. For individuals and Sole Proprietors under the general tax system, the rate is 5%.
The three most common mistakes concern the 5% rate instead of the previous 1.5%, the tax vacation that applies only to groups 1 and 2, and the duration of the levy - three years after martial law is lifted, not one. The cost of a single mistake may seem small, but the penalty is charged for every missed month, and over a year an unnoticed debt can grow into a significant amount together with late-payment interest.
Need reliable accounting support?
The buh.ua team will handle your accounting, monitor changes in legislation, and help you operate without unnecessary tax risks.