Group 1 Individual Entrepreneur in Ukraine in 2026: Taxes and Restrictions

A Group 1 sole proprietor in 2026 is the cheapest and simplest form of legal business in Ukraine. No cash register, no complicated accounting, annual reporting, and tax starting from UAH 332.80 per month.
However, most entrepreneurs do not realize how restrictive this group actually is: the list of permitted services is closed and contains exactly 40 items, and you cannot have any employees. Issue just one invoice to a company instead of an individual - and instead of UAH 332, you will have to pay 15% tax on that income.
Let's break everything down using the 2026 figures: who is eligible for Group 1, what the income limit is, how much the monthly payments actually amount to (spoiler: not UAH 332), and what can cause you to lose Group 1 status.
Who can qualify as a Group 1 sole proprietor
Group 1 of the single tax system is not suitable for everyone, so before registering, it is important to check whether you meet all the legal requirements.
A sole proprietor can operate under Group 1 only if all of the conditions listed below are met simultaneously. The criteria are established by subparagraph 1 of paragraph 291.4 of Article 291 of the Tax Code of Ukraine. There are three conditions, and all of them must be met simultaneously.
These criteria determine whether you can use Group 1 of the single tax system without risking the loss of your right to the simplified taxation system.
The key word in the rule is "exclusively". Not all retail trade is permitted - only retail sales from a trading place at a market. A shop, a sole proprietor's retail outlet in a shopping mall, or sales through Instagram do not qualify for Group 1.
The second key word is "individuals". A Group 1 sole proprietor may serve only ordinary individuals. As soon as you issue an invoice to a company or another sole proprietor, the income is considered to come from an activity that is not permitted for your group.
What services are permitted for a Group 1 sole proprietor
The list of household services is provided in paragraph 291.7 of the Tax Code of Ukraine. That is why, before registering as a Group 1 sole proprietor, it is important to check whether your activity is included in this list. It is a closed list of 40 items: if your service is not included, you cannot provide it under Group 1. A similar KVED activity code will not help. There is no point in listing all 40 items in full here. Below are the main categories of household services:
| Category | What is included |
|---|---|
| Clothing, footwear, textiles | Custom-made production and repair of footwear, garments, leather and fur products, underwear, textile accessories, headwear, knitwear, carpets, leather goods and travel goods |
| Furniture and woodworking | Custom-made furniture, furniture repair and restoration, carpentry and joinery |
| Equipment repair | Audio and video equipment, household electrical appliances, watches, bicycles, musical instruments, other household items and metal products |
| Vehicles | Maintenance and repair of cars, motorcycles, scooters and mopeds on an individual order basis |
| Jewelry and metalwork | Custom-made jewelry and metal products, jewelry repair |
| Household services | Hairdressing services, laundry and linen treatment, cleaning and dyeing of products, fur skin dressing, premises cleaning, domestic help services |
| Other | Rental of personal-use items, photographic services, film processing, funeral services, agricultural and forestry services |
Who is not on the list, although many people think they are: tutors, manicure and pedicure specialists, cosmetologists, massage therapists, custom-order confectioners, photographers providing a full photography service, designers, accountants, and IT specialists.
All of them need Group 2 or Group 3. Hairdressing services are included in the list (item 36), but manicure is not listed as a separate item - this is the most common disputed situation for Group 1.
What is the income limit for a Group 1 sole proprietor in 2026
The limit is calculated based on the minimum monthly wage as of January 1. According to Article 8 of the 2026 State Budget Law, it is UAH 8,647.
167 × 8,647 = UAH 1,444,049 per year. This is the maximum income for a Group 1 sole proprietor in 2026.
The minimum wage is "frozen" at its January figure: even if it is increased during the year, the income limit will remain unchanged until the end of the year. For more details on calculating income, see the article "Exceeding the Income Limit for Sole Proprietors".
How much tax does a Group 1 sole proprietor pay in 2026
This is the main trap in most articles online: they mention only the single tax. In reality, there are three payments, and the single tax itself is the smallest of them.
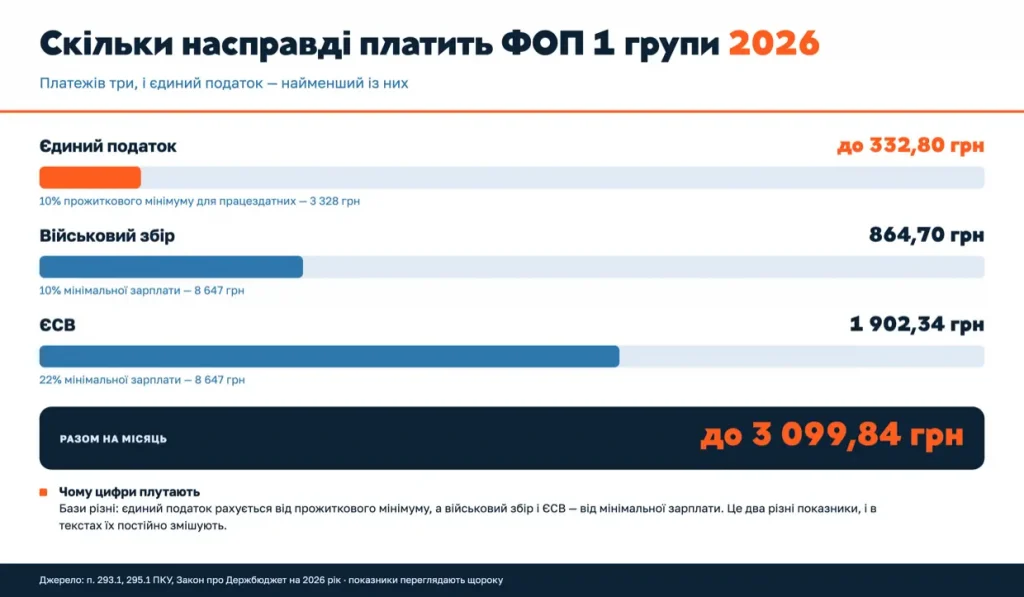
*The amounts in the table are calculated using the figures established by the 2026 State Budget Law: a minimum monthly wage of UAH 8,647 and a subsistence minimum for able-bodied persons of UAH 3,328. These figures are reviewed annually, so all three payments will change in 2027.
Pay attention to the different calculation bases. The single tax is calculated based on the subsistence minimum, while the military levy and the Unified Social Contribution (USC) are calculated based on the minimum monthly wage. These are different figures, and they are frequently confused in articles. Despite the relatively small payment amounts, Group 1 of the single tax system has the strictest restrictions on permitted activities and customers.
Wartime tax relief: what no longer applies in 2026
The right for Group 1 and Group 2 sole proprietors not to pay the single tax has been abolished. It applied from April 1, 2022, through July 31, 2023. Since August 1, 2023, this exemption has remained available only to sole proprietors whose tax address is located in territories affected by hostilities or under occupation according to the list approved by the Cabinet of Ministers of Ukraine.
The right not to pay the Unified Social Contribution has been suspended for 2026. The relevant provision of the Law on the Unified Social Contribution was first suspended for 2025 and then for 2026 under the 2026 State Budget Law. This means that the USC must be paid by everyone in 2026.
For more details about contributions, see the article "Unified Social Contribution for Sole Proprietors: Who Pays, How Much, and When".
Who is exempt from the Unified Social Contribution
Under Article 4 of Law No. 2464-VI, sole proprietors do not pay the Unified Social Contribution for themselves if they receive an old-age or length-of-service pension, are persons with disabilities, or have reached retirement age and receive a pension or social assistance. No application is required for this exemption.
A separate exemption applies to a sole proprietor who simultaneously works under an employment contract. It is applied on a monthly basis and only for those months in which the employer paid the USC for the employee in an amount not less than the minimum contribution. If the employee works part-time and the contribution is lower, the sole proprietor must pay the difference independently.
When a Group 1 sole proprietor must pay taxes
The deadlines differ, and this is the most common reason for accidental tax debts.
| Payment | Payment deadline |
|---|---|
| Single tax | In advance, no later than the 20th day of the current month (for August - by August 20) |
| Military levy | In advance, no later than the 20th day of the current month |
| Unified Social Contribution | Quarterly, by the 20th day of the month following the quarter |
The single tax and military levy are paid in advance, not for the previous month - this is a fundamental difference from the Unified Social Contribution. Both can be paid in advance for a quarter or even for the entire year, but only within the current calendar year.
The tax authority calculates the amounts due based on the rate you selected and the applications you submitted. The penalty for non-payment of the military levy is 50% of its applicable rate.
The wording of the deadlines differs under the law: for the single tax and military levy - "no later than the 20th day inclusive", and for the Unified Social Contribution - "by the 20th day". The safest option is to pay by the 19th, especially when the 20th falls on a weekend. All dates are collected in the "Tax Calendar for Sole Proprietors".
What reports does a Group 1 sole proprietor submit
The single tax payer's tax return is submitted once a year, within 60 calendar days after the end of the year - that is, by March 1. The return for 2026 must be submitted by March 1, 2027.
The same tax return also includes both the Unified Social Contribution and the military levy - no separate reports need to be submitted.
Exception: the return must be filed quarterly if you exceed the income limit, voluntarily switch to Group 2 or Group 3, or leave the simplified taxation system.
Records are kept in any convenient form - income received is recorded monthly. There has been no requirement to register an income ledger with the tax authority since 2021, but you must keep supporting source documents for every amount of income received.
Does a Group 1 sole proprietor need a cash register
No. Paragraph 296.10 of the Tax Code of Ukraine states this very clearly: cash registers (RRO) and software cash registers (PRRO) are not required for Group 1 single tax payers. This provision contains no exceptions based on the type of goods sold.
But this does not mean you can sell anything you want. By definition, Group 1 may only conduct retail sales from a trading place at a market. As soon as you go beyond these limits, you lose the right to use Group 1 - and the cash register issue becomes secondary compared with the 15% tax.
For details on who does need a cash register, see the article "Introduction of Cash Registers for Sole Proprietors".
What is a tax holiday for a Group 1 sole proprietor
This is a legal right not to pay the single tax for certain months. It is established by paragraph 295.5 of the Tax Code of Ukraine and applies to Groups 1 and 2 without employees.
- Vacation - one calendar month per year;
- Illness - if it lasts 30 or more calendar days and is confirmed by an extract from the Electronic Register of Sick Leave Certificates.
This exemption also applies to the military levy - it is not payable for the same periods. However, the Unified Social Contribution must still be paid: the tax holiday does not apply to it.
To use the exemption, you need to submit an application to the tax authority specifying the period of annual leave or temporary incapacity for work. Without an application, the advance payment will simply be assessed.
If the tax for such a month has already been paid, the money is not lost: upon application, it is credited toward future payments.
What restrictions apply to a Group 1 sole proprietor
In addition to the narrow list of permitted services, there is a general "blacklist" for the entire simplified taxation system - paragraph 291.5 of the Tax Code of Ukraine. Activities prohibited under the single tax system include:
- gambling and lotteries, foreign currency exchange;
- production, export, import and sale of excisable goods (with limited exceptions);
- extraction and sale of precious metals, precious stones and minerals;
- financial intermediation, management of enterprises, postal services and fixed-line communications;
- sale of works of art and antiques, organization of touring events;
- security services - a new prohibition effective from January 1, 2026.
Security services deserve a separate mention. They were added to the list by Law No. 4698-IX, and the provision took effect at the beginning of 2026. Materials that list 10 prohibited categories instead of 11 are already outdated.
The single tax system is also unavailable to non-residents and those who have tax debt on the date the application is submitted. Payments are permitted only in monetary form - barter and set-offs are prohibited.
When a Group 1 sole proprietor pays 15% instead of UAH 332
This is the most expensive mistake for a Group 1 sole proprietor. Paragraph 293.4 of the Tax Code of Ukraine establishes a 15% tax rate in five cases.
- income above the UAH 1,444,049 limit - 15% on the excess amount;
- income from activities not entered in the register of single tax payers;
- income received in non-monetary form (barter, set-off);
- income from prohibited activities;
- income from activities not permitted for Group 1.
The last point is the most common in practice, and it is significantly more dangerous than exceeding the income limit. Issue an invoice to a company instead of an individual, provide a service that is not among the 40 permitted services, or sell goods somewhere other than a trading place at a market - and that income becomes subject to a 15% tax.
Therefore, before starting under Group 1, it is important to choose the correct KVED activity codes and enter all required types of activity in the register.
What to do if a Group 1 sole proprietor exceeds the income limit
The procedure is set out in paragraph 293.8 of the Tax Code of Ukraine, and the deadlines are strict.
- pay 15% of the excess amount - in addition to the regular tax, not instead of it;
- choose whether to switch to Group 2 or Group 3 or leave the simplified taxation system altogether;
- submit an application no later than the 20th day of the month following the quarter in which the limit was exceeded.
Example. The limit was exceeded in Q3 2026. The application must be submitted no later than October 20, 2026, and the new group takes effect from October 1, 2026 - that is, from the following quarter.
If you do not submit the application, there is no alternative: Group 1 status is terminated, and the sole proprietor switches to the general taxation system with all of its requirements for accounting for income and expenses.
Not sure whether your sole proprietorship is eligible to remain in Group 1?
The accountants at buh.ua will check your KVED activity codes and actual transactions, assess your risk of being taxed at 15%, and advise whether switching to Group 2 would be more beneficial - before the tax authority does it for you.
How Group 1 differs from Group 2 for sole proprietors
This is one of the key decisions when starting a business, so here is the difference based on the 2026 figures.
| Criterion | Group 1 | Group 2 |
|---|---|---|
| Employees | Not permitted | Up to 10 employees at the same time |
| Who can receive services | Individuals only | Individuals and single tax payers |
| Permitted services | Only household services from the list of 40 items | Any services except prohibited ones |
| Trade | Retail sales only from trading places at markets | Production and sale of goods without being restricted to markets |
| Restaurant business | No | Yes |
| 2026 income limit | UAH 1,444,049 | UAH 7,211,598 |
| Single tax per month | up to UAH 332.80 (10% of the subsistence minimum) | up to UAH 1,729.40 (20% of the minimum monthly wage) |
There is an important limitation for Group 2 as well: a Group 2 sole proprietor can provide services to businesses, but only if those businesses are also single tax payers. A Group 2 sole proprietor cannot provide services to an LLC under the general taxation system - Group 3 is required for that.
How to switch from Group 1 to another group
A voluntary switch is regulated by subparagraph 298.1.5 of the Tax Code of Ukraine: the application must be submitted no later than 15 calendar days before the beginning of the next quarter.
To leave the simplified taxation system and switch to the general taxation system, a different deadline applies - 10 calendar days before the beginning of the quarter.
You can also return to the single tax system, but certain restrictions apply - read more about them in the article "How a Sole Proprietor Can Return to the Simplified Taxation System".
Who Group 1 is not suitable for
Group 1 is not a "budget option for beginners", but a narrowly specialized tax regime. It is not suitable if you:
- plan to hire even one employee;
- work with legal entities or other entrepreneurs;
- provide a service that is not among the 40 items on the permitted list;
- sell goods somewhere other than a market - in a shop, shopping mall, or online;
- expect annual income exceeding UAH 1,444,049.
Another argument against Group 1: the difference in taxes between Group 1 and Group 2 is about UAH 1,400 per month because the Unified Social Contribution and military levy are the same for both. In exchange for those savings, you face much stricter restrictions.
FAQ: the most common questions about Group 1 sole proprietors
Can a Group 1 sole proprietor work with an LLC?
No. Group 1 sole proprietors may provide services only to individuals. Income received from a legal entity or another entrepreneur is considered income from an activity not permitted for Group 1 and is subject to a 15% tax under paragraph 293.4 of the Tax Code of Ukraine.
How much does a Group 1 sole proprietor pay per month in total in 2026?
Up to UAH 3,099.84: single tax up to UAH 332.80, military levy UAH 864.70, and Unified Social Contribution (USC) UAH 1,902.34. The exact amount depends on the rate set by your local council and whether you qualify for any USC exemptions.
Does a Group 1 sole proprietor need a cash register?
No. Group 1 sole proprietors are fully exempt from cash register (RRO) and software cash register (PRRO) requirements - with no exceptions based on the type of goods sold (paragraph 296.10 of the Tax Code of Ukraine). However, remember that permitted trade is limited to retail sales from trading places at markets.
Can a Group 1 sole proprietor provide manicure services or work as a tutor?
No. The list of 40 household services is closed: it includes hairdressing services, but manicure is not listed as a separate item, nor are tutoring, cosmetology, or massage services. These activities require Group 2 or Group 3.
Does the wartime tax exemption for Group 1 still apply?
The right not to pay the single tax was abolished from August 1, 2023 - it remains available only to sole proprietors whose tax address is located in territories affected by hostilities or under occupation. The right not to pay the Unified Social Contribution has been suspended for 2025 and 2026, so the contribution must be paid by everyone.
When does a Group 1 sole proprietor have to file a tax return?
Once a year, within 60 calendar days after the end of the year, meaning by March 1. For 2026, the deadline is March 1, 2027. The same tax return also includes the Unified Social Contribution and the military levy.
What happens if the income limit is exceeded?
The excess amount is subject to a 15% tax, and you must submit an application to switch to Group 2 or Group 3 no later than the 20th day of the month following the quarter in which the limit was exceeded. If the application is not submitted, the sole proprietor switches to the general taxation system.
Conclusion
Group 1 for sole proprietors in 2026 is the cheapest form of legal business: up to UAH 3,099.84 per month including the Unified Social Contribution and military levy, annual reporting, no cash register, and no complicated accounting.
The price of this simplicity is strict limitations: no employees, only individuals as customers, a closed list of 40 permitted services, and retail trade exclusively from trading places at markets. The 2026 income limit is UAH 1,444,049.
The main risk is not exceeding the income limit, but going beyond the permitted activities: a single invoice issued to a company or
a service that is not on the permitted list results in a 15% tax on that income. Therefore, before registering, it is worth carefully assessing whether your activity really fits within the limits of Group 1 - the difference compared with Group 2 is about UAH 1,400 per month, and in many cases the savings are simply not worth it.
If you are unsure whether Group 1 of the single tax system is right for you, it is better to compare it with other taxation regimes before registering as a sole proprietor.
Don't want to figure out tax groups, rates, and deadlines on your own?
Entrust your accounting to the buh.ua team. We will choose the optimal tax group for your business activity, register you as a sole proprietor, handle your accounting, and keep track of all payments and reporting deadlines.